Dear Valued Clients and Friends –
Our 21st annual “money manager week” here in NYC is underway, and today we started with nine different meetings (four portfolio strategy teams at Apollo, four at Blackstone, and one at Goldentree). I am going to devote the Friday Dividend Cafe a week from this coming Friday to a full recap, and in the meantime we are in the zone here in NYC!
Dividend Cafe on Friday did a little past, present, and future look at The Bahnsen Group, discussed the closing of our long-awaited transaction with Hightower, and reiterated the forward vision of our independent company. The written version is here (yes, this is still my favorite), the video is here, and the podcast is here.
Off we go …
|
Subscribe on |
Market Action
- Markets opened down a tad this morning and rebounded throughout the day
- The Dow closed up a pinch (+0.18%) with the S&P 500 up +0.66% and the Nasdaq +1.05%
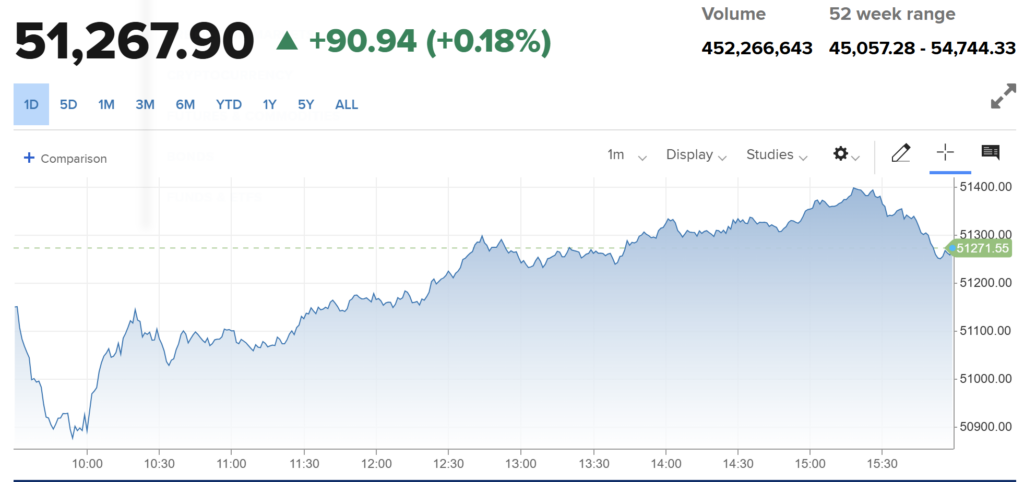
*CNBC, DJIA, October 5, 2026
- With earnings season getting ready to start, we have already seen expectations adjusted higher +1.8%. As a general rule of thumb, the bar is highest where expectations have been moved up already, and the opportunity for positive surprise is most present where there have been downward revisions.
- The drop in alternative asset managers over the last 3-4 weeks is surely related to higher bond yields and what that does to expectations of already stalled realizations. That said, asset gathering remains strong (where fees come from) and redemptions from retail private credit have slowed substantially.
- But where higher rates have hurt alternative asset managers, they should help bank stocks where net interest margin will expand (what we call a low deposit beta – they can benefit from lending at higher rates but not suffer proportionately in the interest rates paid to depositors). Investment banking activity also likely slowed in Q3.
- The ten-year bond yield closed today at 5.31%, up 3 basis points on the day
- Top-performing sector for the day: Materials (+1.22%)
- Bottom-performing sector for the day: Real Estate (-0.44%)
- It has not just been tech; health care has also exploded over the last couple of weeks.
Public Policy
- President Trump announced a “Super Intelligence Force” over the weekend to serve as a coordinating body with the federal government on American development of AI. The general concept of more governmental bodies that are nebulous, ambiguously empowered, and surrounded with vague descriptions (“coordinating federal efforts”) is usually one I roll my eyes at – and perhaps this will prove to be the same. However, having Jay Clayton serve as the chair is a step in the right direction (I believe Jay to be a serious person and not one who would take this if it were merely cosmetic). There are some on the force I do not know, some I do not like, and some I like a great deal. As is often the case, time will tell if this group is:
- Serious and useful,
- Serious and un-useful,
- Unserious and problematic,
- Unserious and un-useful, or
- Serious and problematic.
I hope it is A. All options are on the table (and I think I covered all combos).
- There are few political pundits I respect more than Mark Halperin, so his general sentiments here are worthy of being shared. Everyone you talk to sees North Carolina as a goner for the Republicans. Mark now suggests that the second most likely to flip red-to-blue is … Kansas!!!! He then lists the vulnerabilities (in order) after that as Ohio, Alaska, Iowa, Texas, and Maine. Maine being the seventh most vulnerable is a testimony to Susan Collins’ resilience. Will the Democrats hold Michigan and New Hampshire? And if so, will they flip three of those six? All of it is very hard to handicap (in total) as more or less than a 50-50 proposition. If the Democrats need +4 (they do) for a Senate majority and the range of outcomes is +2 to +6, then you can see why 50/50 is the fair level of odds.
Economic Front
- It was not a good jobs report Friday, as 29,000 new jobs were created in September versus expectations of 90,000. And once again, the revisions for past months were to the downside (60,000 reduced from July and August). The unemployment rate ticked up to 4.2%.
- It is worth noting that the household survey and ADP number showed better private-sector results last month. It is also worth noting that the labor force expanded by 485,000.
- Average hourly earnings were up just +0.1% on the month and are up +3% year-over-year, essentially level with (or just below) the increase in the price level
- We are averaging 40k new jobs a month now (last year), though it has picked up to 65k in the last six months. We really need to see 150-200k/month to feel on firmer footing.
- Shipping costs have exploded all over the world and are one of the biggest inputs to higher prices that we have.
- ISM Services came down -0.5% in September. Construction of data centers (strong) is helping here, but construction of everything else (weak) is hurting.
Federal Reserve
- After the soft jobs report on Friday, the expectations for a rate hike in October fell (now at 22% in the futures market versus previously well above 50%). Expectations are still around 85% for a rate hike by the end of the year.
- I should say, with vice chair Jefferson, John Williams of NYC, and Michelle Bowman (three Fed governors) all basically saying the Fed is not going to hike in October, I am surprised the futures market is even holding a 22% expectation that they might. And I have to say, if the intent of the Warsh Fed is to avoid forward guidance, it does not appear these three Fed governors got the memo.
Oil and Energy
- WTI Crude closed at $89.21, down -2.09%
- Midstream was flat last week in a down week for markets and oil. It was a very bad month overall, in concert with all rate-sensitive sectors moving inversely to bond yields.
- One thing that has now come up in two company reports and one analyst report I have read in the last week is optimism for the ball moving the right way when it comes to permitting reform. Progress here will be a very good thing for the industry (and the country).
- South Korea disputed the President’s claim that they were invested $44 billion in an Alaska LNG project.
Ask TBG
| “While technologically still years or even decades away, shouldn’t something like capturing solar in satellites and powering data centers be included in the S&P Energy sector weighting? More generally, are there disrupters that might be weighing on the lower index percentage of energy that you described in last week’s Dividend Cafe?” ~ David H. |
| I don’t think sector indices can (or should) include a company based on something they may do or want to do, but yes, should it come to fruition, those sector judgment calls are made all the time (subject to the totality of index methodology criteria). |
On Deck
- I can tell you what I have on deck this week – meetings. Lots of meetings. Lots of recap coming.
- This coming Friday’s Dividend Cafe will look at the drama in the bond market over the last few weeks (months?), what it means for investors, what is causing it, and where we go from here.
More to Chew on
Reach out with any questions and have a happy Monday night!
With regards,
David L. Bahnsen
Chief Investment Officer, Managing Partner
The Bahnsen Group
www.thebahnsengroup.com
The Dividend Cafe features research from S&P, Baird, Barclays, Goldman Sachs, and the IRN research platform of FactSet.